In short: Capital allowances on warehouses let a limited company deduct the cost of qualifying plant and fixtures from its taxable profits. The warehouse structure itself does not qualify as plant, but most of what makes it work does: racking, lighting, power, heating, dock equipment, security and fire systems, conveyors and much of a typical fit out. How much relief you get, and when, depends on how each item is classified, whether it is new or second hand, and whether you built, bought or lease the building. The structures and buildings allowance then picks up much of the construction and refurbishment cost that plant allowances cannot reach.
What are capital allowances on warehouses?
Capital allowances are the tax system's replacement for depreciation. Your accounts write assets down over their useful life, but that depreciation is added back when corporation tax is calculated and capital allowances are claimed instead. For a logistics business that invests heavily in property and equipment, they are often one of the largest single items in the tax computation.
Warehouse capital allowances are less about the building and more about what goes inside it. The tax rules draw a line between the premises in which a trade is carried on and the plant with which it is carried on. Walls, floors, roofs and land sit on one side of that line. Equipment that performs a function in the business sits on the other. In practice, most warehouse spending falls into four groups:
- main rate plant and machinery, such as racking, conveyors, CCTV and office furniture
- special rate expenditure, which includes integral features such as electrical and lighting systems, heating, cooling and lifts, along with thermal insulation
- structures and buildings, which can qualify for the structures and buildings allowance rather than plant allowances
- costs that attract no allowances at all, most notably the land
Getting each item into the right group is where most of the value in a claim is won or lost, and it is where HMRC focuses when it reviews one. It is also one of the areas where specialist accountants for third party logistics companies tend to add the most value, because the classification questions are specific to how warehouses are built and used.
Which warehouse fit out costs qualify for capital allowances?
A capital allowances warehouse fit out claim works best when it is built up from the detail rather than estimated. Contractors' final accounts rarely separate qualifying and non qualifying work in the way the tax rules need, so the analysis usually has to be reconstructed from invoices, drawings and specifications. These are the main categories in a logistics fit out.
Racking and shelving
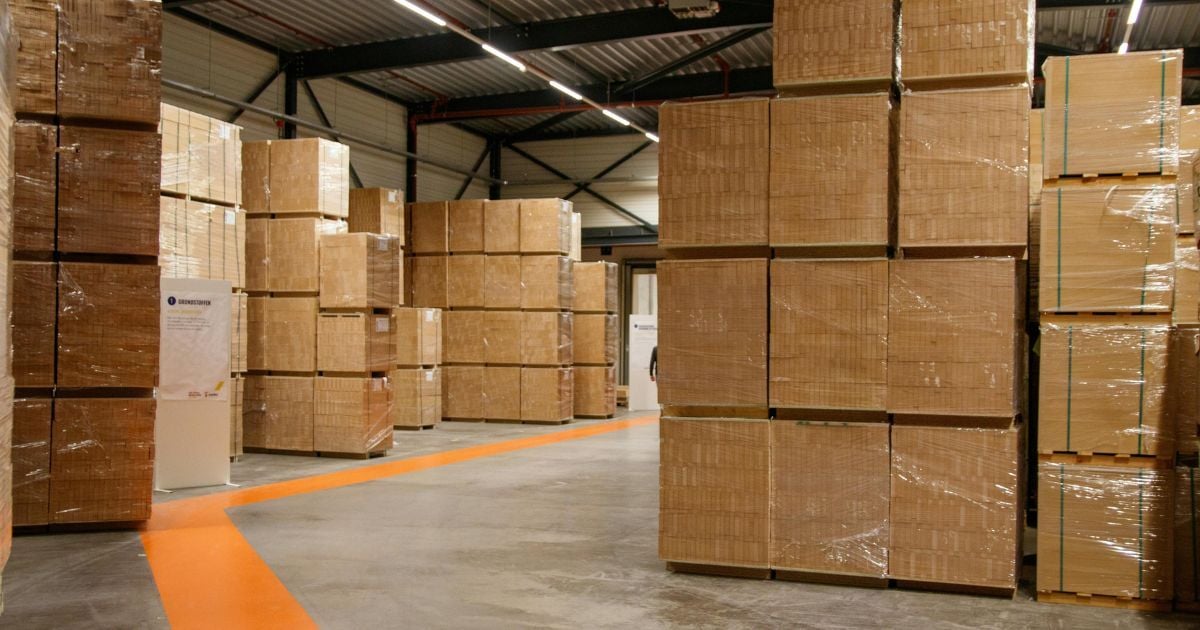
Capital allowances on racking are generally straightforward. Pallet racking, shelving, carton flow systems and similar storage equipment are treated as plant because they perform a function in the business: holding goods so they can be stored and picked. New racking bought by a company normally qualifies as main rate expenditure.
The picture changes in a few situations. Racking bought second hand does not qualify for full expensing, although other allowances remain available. Racking that has been relocated, reconfigured or partly sold on raises questions about disposal values. And in rack supported buildings, where the racking also carries the roof and cladding, part of the cost may be treated as structure rather than plant. Each of these needs looking at on its own facts.
Mezzanine floors and storage platforms
Mezzanines sit on one of the more contested boundaries in capital allowances. A floor is normally part of the building, yet a freestanding storage platform installed to hold stock or equipment can have a strong argument for being plant. The answer turns on how the mezzanine is constructed, whether it can be removed and what it is used for. Staircases, balustrades, lighting and fire protection associated with a mezzanine are assessed separately, and some of those elements can qualify even where the deck itself does not.
Lighting, power and heating
Electrical systems including lighting, space heating, cooling and ventilation, hot and cold water systems and lifts are integral features. They qualify for allowances, but at the special rate rather than the main rate. For a warehouse moving to LED lighting or upgrading its electrical distribution, this matters because special rate expenditure is relieved more slowly unless another allowance is used against it.
Replacing an integral feature can also be treated differently from an ordinary repair. Where a large part of a system is replaced within a short period, the whole cost is treated as capital rather than as a deductible expense. That can work for or against you depending on the rest of your position, so major replacements are worth planning rather than letting them happen piecemeal.
Dock and loading bay equipment
Dock levellers, dock shelters, vehicle restraints and buffers are usually plant, because they exist to move goods rather than to form part of the premises. Loading bay doors need more care. A door is ordinarily part of the building, but powered doors and the mechanisms that operate them can contain qualifying elements. Weighbridges generally qualify as plant, while the pits and yard surfaces around them do not.
Security, fire safety and access control
CCTV, intruder alarms, access control systems and fire alarms normally qualify as main rate plant, and sprinkler systems are specifically recognised as capable of being plant. Perimeter fencing, gates and barriers are generally treated as structures instead, though they may still attract the structures and buildings allowance.
Temperature controlled space
Cold chain operators often have some of the most valuable, and most complicated, claims. The key distinction is whether equipment serves the building or serves the goods. Refrigeration plant installed to keep stock at a controlled temperature can be treated differently from general cooling and air conditioning, which is an integral feature. Cold room panels, thermal insulation and the refrigeration plant behind them each need classifying on their own terms.
Automation, conveyors and sortation
Conveyors, sortation lines, automated storage and retrieval systems, pick to light equipment and the control systems that run them are plant. The building work needed to accommodate them, such as strengthened slabs, pits and openings, is often overlooked. Some alteration work carried out to install plant can qualify alongside the plant itself, which is easy to miss if the project is booked as a single line in the accounts. Where an automation project involved solving genuine technical problems, the development work may also be relevant to R&D tax relief for logistics and warehouse technology, which is a separate claim handled through our tax relief team.
Vehicles and electric vehicle charge points follow their own rules, which we cover in our guide to fleet tax and capital allowances.
Which capital allowances apply to warehouse spending?
Once each item is classified, the next question is which allowance to use. A limited company has more options than an unincorporated business, and the choice between them affects both the size and the timing of the deduction.
Full expensing gives relief on the entire cost of new and unused main rate plant in the year it is bought, with no upper limit. The equivalent first year allowance for special rate assets relieves half the cost upfront, with the balance going into the special rate pool. Both are available only to companies, which is one of several reasons scaling logistics operators tend to trade through a limited company.
The annual investment allowance gives full relief in the first year up to an annual limit, and unlike full expensing it covers second hand assets. Where a company has both main rate and special rate spending in the same period, the way these allowances are allocated can make a real difference to the result. The limit is also shared between companies in a group, which catches out businesses that run warehousing and transport through separate entities.
Anything not covered by a first year allowance or the annual investment allowance goes into the main pool or the special rate pool and is relieved gradually through writing down allowances. Recent Budget changes reduced the main pool writing down rate and introduced a new, smaller first year allowance for main rate assets that fall outside full expensing, most notably plant bought to lease out. Second hand assets and cars remain excluded from it. For most 3PLs buying new equipment for their own operations, full expensing and the annual investment allowance still do the heavy lifting, but a slower pool rate makes it more important than ever to capture relief upfront wherever the rules allow. HMRC's overview of capital allowances sets out the current allowances and rates.
Full expensing does have a sting in the tail. When an asset that has been fully expensed is sold, the sale proceeds are generally brought into tax in full at that point. Selling racking on when you move sites, or leaving a fit out behind at the end of a lease, needs planning rather than simply booking a profit on disposal.
What about the warehouse building itself?
The building shell, foundations, floor slab, yard surfacing, roads and fencing do not qualify for plant allowances. They can qualify for the structures and buildings allowance, which gives a flat annual deduction over a long period for the cost of constructing, extending, converting or renovating non residential buildings. Land and the cost of acquiring it are excluded.
The structures and buildings allowance depends on paperwork. A claimant needs an allowance statement recording when the building first came into qualifying use and the amount of qualifying expenditure, and that statement needs to pass to later owners. The allowance also has a knock on effect when the property is eventually sold, because allowances claimed are brought into the capital gains calculation. For a logistics company that holds its warehouse in the trading company or in a separate property company, that interaction deserves thought long before a sale.
How do capital allowances on commercial property work when you buy a warehouse?
Buying a warehouse means buying the fixtures inside it: the electrical systems, lighting, heating, fire systems and more. A buyer can claim capital allowances on those fixtures, but only if strict conditions are met. Where the seller was entitled to claim on them, the seller must have pooled the expenditure, and the buyer and seller must fix the value of the fixtures, usually through a joint election, within a strict time limit after completion. If those steps are missed, the buyer's entitlement can be lost permanently, and so can the entitlement of every later owner.
This makes capital allowances on commercial property a negotiation point rather than an afterthought. The value agreed in the election affects both sides, and sellers do not always have an incentive to be generous. Pre contract enquiries, warranties and the election itself need agreeing alongside the purchase, which means your accountant, your solicitor and, where needed, a specialist surveyor working to the same timetable.
Where the seller was never entitled to claim, such as a pension fund or a charity, a buyer may instead be able to claim on a just and reasonable apportionment of the price. Unclaimed allowances in second hand buildings are one of the most valuable and least understood opportunities in logistics property, and they are something our tax advisory team looks for whenever a client is buying premises.
Can a tenant claim capital allowances on a warehouse fit out?
Most 3PLs lease rather than own, and a tenant who pays for fixtures in a leased warehouse can usually claim capital allowances on them, even though the fixtures legally become part of the landlord's property. That covers much of a typical tenant fit out: electrical and lighting upgrades, heating, fire and security systems, and qualifying alterations needed to install racking and automation.
The complications sit at the edges. If the landlord contributes towards the fit out, the portion funded by the landlord generally cannot be claimed by the tenant. Incentives in the lease need reading carefully to establish who actually bore the cost. At the end of the lease, fixtures left behind, reinstatement obligations and dilapidations settlements can all have tax consequences. Agreeing the treatment when the lease is signed is far easier than unpicking it on exit. If you are taking your first unit, our guide on how to start a logistics company covers the wider set up decisions.
What mistakes cost logistics companies relief?
The same problems come up repeatedly when we review claims for warehousing and fulfilment businesses.
- Treating a fit out as one cost. A single property or leasehold improvements line in the fixed asset register hides the split between main rate, special rate, structures and land.
- Missing the alterations. Building work needed to install plant is often left in the property cost when some of it can follow the plant.
- Confusing repairs with capital. Some warehouse spending can be deducted as a repair, while some apparent repairs are capital. Getting this wrong can lose relief or invite an enquiry.
- Losing the paperwork. Allowance statements, contractor breakdowns and purchase elections are hard to recreate years later.
- Forgetting disposals. Racking and equipment sold or scrapped on a site move needs recording, especially where it was fully expensed.
Most of these are avoidable with a fixed asset register that is maintained through the year rather than rebuilt at the year end. That is where properly structured management accounts for logistics companies, supported by reliable bookkeeping, earn their keep.
How do capital allowances fit into wider planning for a logistics company?
Capital allowances belong to the fourth stage of our 5 Stage Success Journey, Tax Advisory, but the decisions that drive them are made much earlier. The timing of a new site, a racking expansion or an automation project affects your tax bill, and the relief in turn affects the cash available to fund the next project. That is why we model allowances inside forecasts rather than working them out after the event, as part of our business advisory work. Our guide to cash flow and working capital management for logistics companies covers the forecasting side.
They matter at the far end of the journey too. When an owner comes to sell, buyers and their advisers will look at the fixed asset register, the elections made on property purchases and any balancing charges waiting to crystallise. Tidy capital allowances records are as much a part of exit planning as they are of the annual tax return.
If you are planning a new site, it is also worth looking at what it costs to run a warehouse, because the capital decisions you make on the fit out shape your running costs for years afterwards.
Frequently asked questions
Can you claim capital allowances on a warehouse?
A limited company cannot claim plant and machinery allowances on the warehouse structure itself, but it can claim on the qualifying plant and fixtures inside it, such as racking, lighting, electrical systems, heating, dock equipment and security systems. Construction, extension and renovation costs for the building may qualify for the structures and buildings allowance instead.
Does racking qualify for capital allowances?
Yes. Pallet racking and shelving are usually treated as main rate plant and machinery, so new racking bought by a company can normally be relieved in full in the year of purchase through full expensing. Second hand racking, and racking that supports the building structure, are treated differently.
Is warehouse lighting an integral feature?
Yes. Electrical systems, including lighting, are integral features and fall into the special rate category. They qualify for capital allowances, but relief is given more slowly than for main rate plant unless the annual investment allowance is allocated to them.
Can a tenant claim capital allowances on a warehouse fit out?
Usually, yes. A tenant who pays for qualifying fixtures in a leased warehouse can generally claim allowances on them. Any part of the cost met by a landlord contribution normally cannot be claimed by the tenant, and the position at the end of the lease needs planning.
Can I claim capital allowances on second hand racking?
Second hand racking does not qualify for full expensing, but a company can still claim through the annual investment allowance or, beyond that, through writing down allowances in the main pool.
What happens to capital allowances when you buy a warehouse?
A buyer can claim on the fixtures in the building, but where the seller was entitled to claim, the seller must have pooled the expenditure and both parties must fix the value of the fixtures, usually by joint election, within a strict time limit after completion. Missing these steps can mean the allowances are lost for good.
How can Pulse help with warehouse capital allowances?
We work with warehousing, fulfilment and transport businesses across the UK from our offices in the North East and London. Whether you are fitting out a new site, buying a building or reviewing what has been claimed in the past, our 3PL accounting and tax team can work through the detail and show you where the relief sits. London operators can read more in our guide for 3PL accountants in London, or you can book a conversation with our team.